What insurers really look for—and which factors matter more than you think
When people think about life insurance pricing, the usual suspects come to mind: age, smoking, and major health conditions. And while those absolutely matter, they’re only part of the story.
In reality, insurers are looking for
patterns, especially patterns that suggest long-term health risk or a lack of stability. What’s surprising is that many personal factors aren’t particularly dangerous on their own, but when viewed together they help paint a picture of how predictable (or unpredictable) your health and lifestyle might be over time.
Some of these factors carry significant weight in pricing your policy, while others play a smaller, supporting role. Understanding the difference can help you better anticipate your costs, and even improve your insurability.
Factors Life Insurers Weigh Heavily
These are the areas that can meaningfully impact your premiums or even your eligibility for life insurance coverage.
1. Use of mobility devices
If you use a wheelchair or walker, the focus isn’t the device—it’s the reason behind it. Chronic conditions like neurological disorders, cardiovascular disease, or severe arthritis can significantly increase risk. Insurers will look closely at diagnosis, severity, and stability.
One important nuance: insurers try to distinguish between temporary and long-term need for mobility assistance, and that distinction can meaningfully affect your rates. If the need is short-term or recovery-based (example: recovery from surgery), it may have little to no long-term impact on your pricing.
2. Smoking, Alcohol, and Substance Use
These habits are strongly tied to long-term mortality risk, making them central to underwriting decisions.
- Smoking remains one of the biggest cost drivers
- Heavy alcohol use can raise red flags
- Drug use (past or present) may limit options or increase premiums
3. Sleep Disorders (Especially Untreated)
Conditions like sleep apnea can have a bigger impact than many expect, particularly if untreated. However, consistent treatment (like CPAP use) can improve your rating.
4. Prescription Medication History
Medications tell insurers a lot about your health:
- Blood pressure and cholesterol meds indicate cardiovascular risk
- Mental health medications may prompt deeper review
- Chronic pain management can signal ongoing health concerns
5. Driving Record
A history of DUIs, reckless driving, speeding tickets, or multiple accidents suggests risk-taking behavior and can noticeably increase premiums.
6. High-Risk Hobbies and Activities
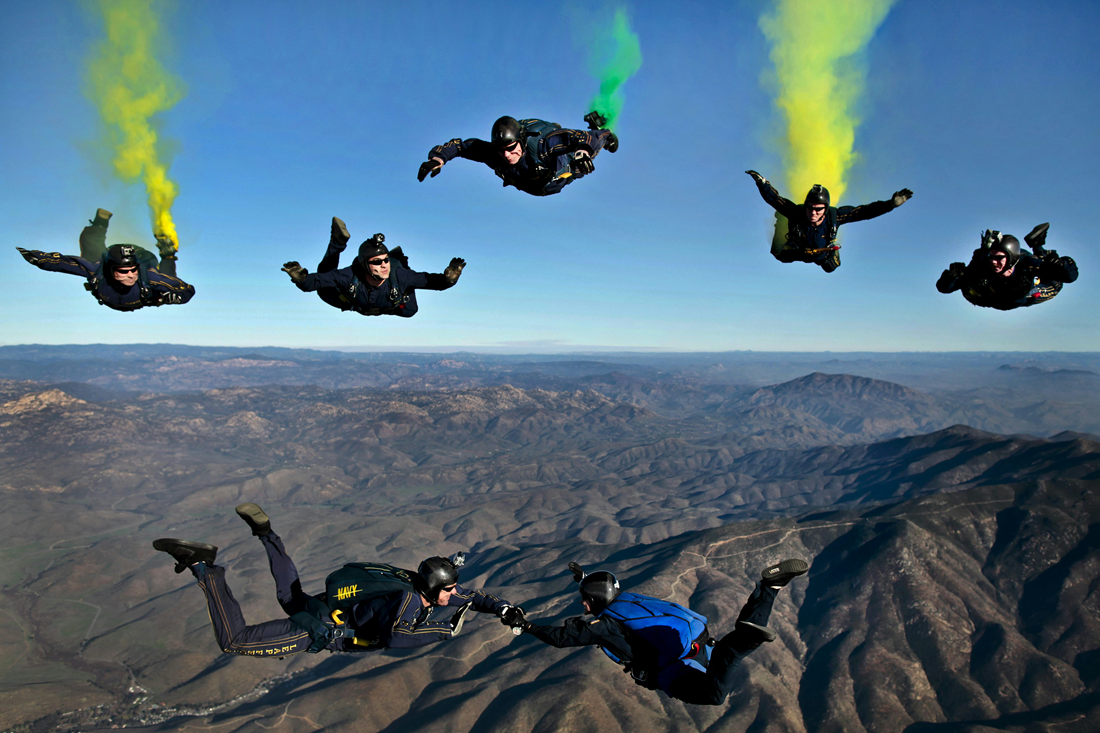
Activities like scuba diving, private aviation, rock climbing or mountaineering, and motorcycle riding introduce a higher likelihood of accidental death, which insurers take seriously.
7. Hazardous Occupations
Jobs that involve physical danger, such as working at heights, with heavy machinery, with hazardous materials, or in unpredictable environments, can significantly impact life insurance costs. As with other factors, insurers look beyond job titles to understand your actual day-to-day responsibilities and level of risk exposure.
Factors That Matter—but Less Than You Might Think
The following elements still play a role, but usually as part of a broader picture rather than as standalone deal-breakers.
1. Sleep Habits (General)
While diagnosed disorders matter, occasional poor sleep or irregular schedules typically won’t move the needle much on their own.
2. Travel Habits
Travel to high-risk regions or frequent international trips may be considered, but for most people, it’s a minor factor unless travel is extreme or ongoing.
3. Weight and Body Composition
Your weight matters, but it’s often evaluated alongside other health indicators. Small fluctuations or being slightly outside “ideal” ranges typically won’t dramatically affect your rate.
5. Mental Health History (Stable and Managed)
A well-managed condition with consistent treatment is often viewed far more favorably than people expect. Stability matters more than the diagnosis itself.
6. Financial Background or Credit Indicators
Some insurers use this data, but it’s generally a secondary factor and varies by state and company.
What To Do With This Information
Life insurance underwriting isn’t about one single factor, it’s about the
overall story your data tells.
A risky hobby alone may not significantly increase your premium. Neither will occasional poor sleep or a stressful job. But when multiple risk signals stack up—like unmanaged health conditions, inconsistent habits, or a pattern of risky behavior—that’s when costs start to climb.
The good news? Many of the most important factors are
within your control. Managing your health, following treatment plans, and maintaining consistent habits can go a long way toward improving both your eligibility and your rates.
And perhaps most importantly, it pays to shop around. Different insurers weigh these factors differently, so the same person can receive very different offers depending on the company. We are here to help you understand your options and the application process.